RBA waves white flag
This is pretty technical but might require us all to look at a future with rising interest rates, and it could happen sooner than expected.
The RBA met on Tuesday this week and decided to:
- Maintain the cash rate target at 10 basis points or 0.1%
- Continue the purchase of $4 billion of Government securities per week until mid February 2022
- Discontinue the yield target of 10 basis points for the April 2024 Australian Government bond
The Australian economy is recovering after the interruption caused by multiple COVID-19 outbreaks. As vaccination rates increase further and restrictions are eased, the economy is expected to bounce back relatively quickly. The central forecast is for GDP growth of 3 per cent over 2021 and 5½ per cent and 2½ per cent over the following two years. Bond yields have increased recently, and bond market volatility has also risen significantly.
The decision to discontinue the yield target reflects the improvement in the economy and the earlier-than-expected progress towards the inflation target. Given that other market interest rates have moved in response to the increased likelihood of higher inflation and lower unemployment, the effectiveness of the yield target in holding down the general structure of interest rates in Australia has diminished. This is code for the RBA reducing their influence and allowing the market to price in future interest rate increases and is likely to see fixed mortgage rates rise even further as banks price in an earlier official RBA interest rate rise.
New Zealand, Norway, South Korea and Singapore recently lifted official interest rates, while the UK is considering a move as early as next month and the US Federal Reserve is expected to start withdrawing some stimulus later this year. In Australia, longer-term fixed-rate home loans are already becoming more expensive even though short-term or variable rates have been falling as shown in the table below.
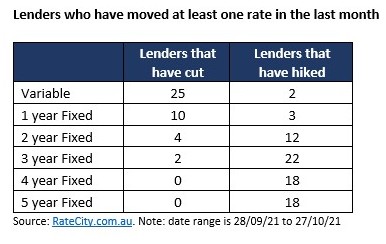
The most recent figures from RateCity show that 18 lenders have increased their four and five-year fixed mortgage rates over the past month, while none have cut them, and 22 lenders have increased their three-year fixed mortgage rates, and 12 lenders have increased their two-year fixed rates. This suggests lenders are anticipating the RBA will start increasing the cash rate in two year’s time. The NAB has brought forward its forecast date of the first official rate rise to mid-2023, but it then predicts rates will climb quickly to 2% by the end of 2024. If passed on in full by lenders, such a rate increase would add about $500 a month onto the repayments for a $500,000 30-year mortgage.
This will obviously depend on whether the economy continues to grow and the rate of inflation, but it does show that the current low interest rates won’t stay low for much longer.
More Articles

Complex rules of small business CGT concessions can present challenges
The complex rules around small business capital gains tax concessions can eliminate tax on a business sale and...

IGR predicts drawdowns will be major source of retirement income
Drawdowns from superannuation are projected to increase to almost six per cent of gross domestic product (GDP...

Retirees hardest hit by inflation
Retirees are being hit harder by rising prices than the general population, with the costs that dominate their...

The retirement gap we don’t talk about
Retirement confidence isn’t just about your nest egg, it’s about your plan. Retirement...

The three phases of retirement: Key decisions at every stage
Retirement starts long before your last day at work. Retirement starts long before your last day at...

Children as SMSF dependents very complex
The definition of children as dependants under superannuation law is not straightforward when dealing with...

Two Cautionary Tales About Resources Important to Anyone Using a Domain Name or Website
This warning is new, but the reason for forgetting to renew a domain name isn’t. 1. Not renewing...

Check out the smartest species on earth: Data from 200M BC to 2026
Check out the evolution of animal intelligence from the Jurassic Period (~200 million years ago) to 2026...
Heathmont Financial Services Pty Ltd (ABN 68 106 250 104) trading as Heathmont Financial Services is a Corporate Authorised Representative (No. 262098) of Knox Wealth Management Pty Ltd (ABN 74 630 256 227), Australian Financial Services Licence Number (AFSL) 513763.
Julian McGoldrick is an Authorised Representative (No. 262098) of Knox Wealth Management Pty Ltd AFSL 513763.